ICAI President Revelations on NFRA Consultation Paper and Accounting Standards
Icai president published a new video on icai ca tube 2 days back that is on 7th oct 2021 to communicate some important developments in the profession. Dear viewers please read the article till end there is an important instruction by President regarding comments to be sent on consultation paper on audit of small companies.
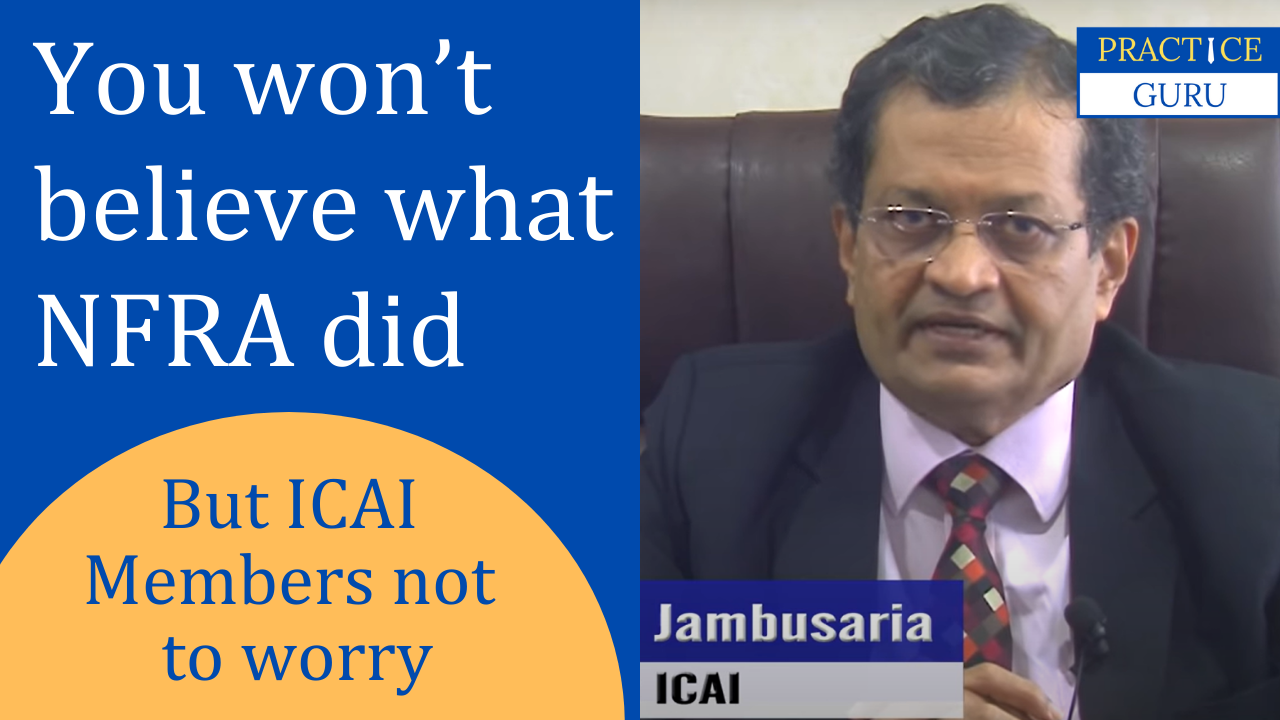
He made members aware about a post by NFRA on the website of Press Information Bureau right from 27 September 21 when the Then NFRA Chairman issued this press release in the Press Information Bureau. ICAI president rightly observed that there is a lot of discussion and concern among the members on this matter.
He then pointed out that The then NFRA Chairman mentioned that he has sent back the Approach paper for revision of the existing accounting standards to Icai, asking it to carry out regulatory impact assessment and hold extensive nationwide discussion.
The president updated that Accounting Standards Revision process commenced in 2006 and the Approach paper developed by Icai was approved by Nacas when it was in existence. Much efforts went into the revision of 18 accounting standards over five years for which new process of issuing exposure drafts and seeking comments of stakeholders was followed.
He further said that Then NFRA Chairman did not think it fit to bring the revised accounting standards for discussion at the Nfra Board meeting as recent as on 20th September 21, wherein the Parttime members were also present.
He assured members that an appropriate reply is being drafted and the revised the accounting standards are being sent back to NFRA for its consideration.
All of you are aware about the fact that
NFRA has issued a Consultation Paper on 29th September 2021 on Statutory Audit and Auditing Standards for Micro, Small and Medium Companies (MSMCs) for comments by its stakeholders. NFRA has done an analysis of MCA data and focus of the analysis is companies with Net worth below Rs. 250 crores. These companies are referred to as Micro, Small and Medium companies (MSMCs) for the purpose of this Consultation Paper.
They have discussed lot of data of filings by small companies and audit fees levels and indebtedness status of companies. Indebtedness indicates the public money involved in the companies. They have given comparisons with other countries too. And at last, They have come to a conclusion that audit for small companies is not required.
In this matter in the video the President of ICAi said that these veiws
cannot be regarded as the view of nfRA. This view was never brought for discussion at the NfRA Board. NFra does not have jurisdiction over micro, small and medium companies as per the companies act 2013 and nfra rules. It is not within the purview of nfra to recommend whether audit of certain categories of companies is required or not. President further informed that ICAi is not communicated of any such thought process in the Ministry of Corporate Affairs.
ICAi is in discussion with appropriate authorities in the Ministry of Corporate Affairs in this matter.
He reiterated that icai would like to have good coordination within nfra for which discussions will be held with them. This was done in the past and Icai will continue to have channels of discussions open with nfra.
At last he requested icai members to have patience and not to send diverse communications to NfrA or to the Ministry individually. The Council is doing everything that is required to be done in the given situation in this matter.
Very importantly he said if members have any views on the matter, please write to icai at [email protected]. Icai will be happy to consider them for the purpose of representation to NFRa and to the Ministry.
Disclaimer: The information contained in this website is for general information purposes only. The information is provided by PracticeGuru and while we endeavour to keep the information up to date and correct, we make no representations or warranties of any kind, express or implied, about the completeness, accuracy, reliability, suitability or availability with respect to the website or the information, products, services, or related graphics contained on the website for any purpose. Any reliance you place on such information is therefore strictly at your own risk. In no event will we be liable for any loss or damage including without limitation, indirect or consequential loss or damage, or any loss or damage whatsoever arising from loss of data or profits arising out of, or in connection with, the use of this website.
Grow your practice with PracticeGuru
Write for PracticeGuru
Send your articles to [email protected]. We publish them on our website with credit to you. Read all articles.
